When Should a Kenyan Collection Agency Move From Manual Tracking to Collection Software?
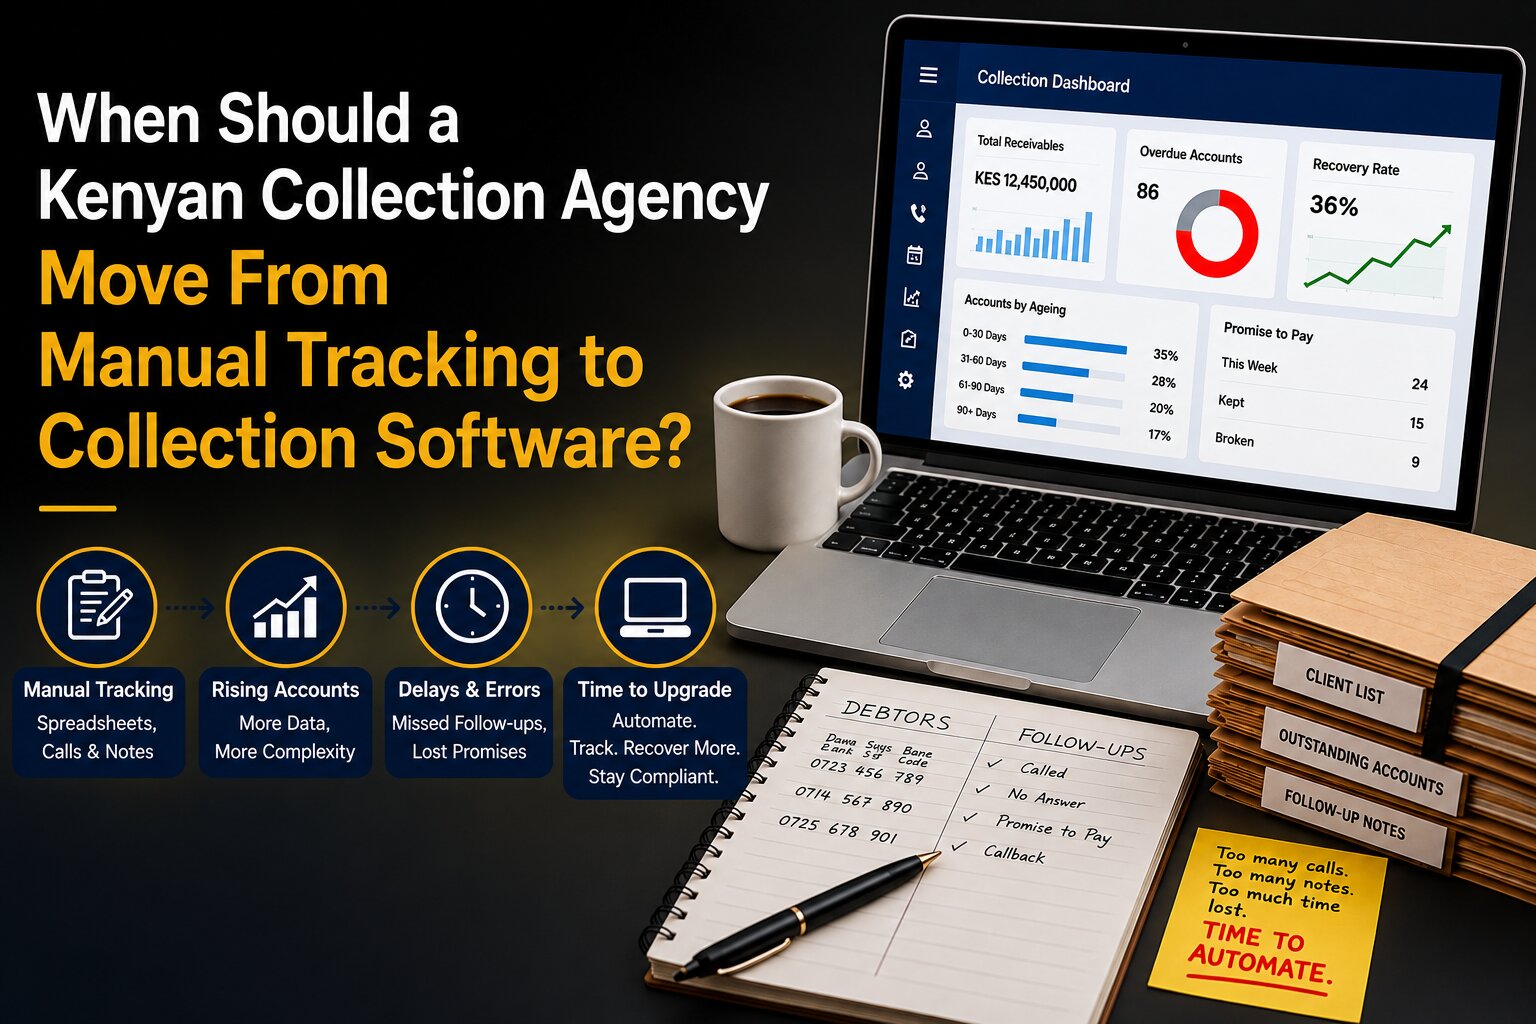
Spreadsheets, phone calls, WhatsApp messages and notebooks are often enough when a collection agency is managing a small portfolio. They are familiar, inexpensive and easy to start with. The challenge usually appears as the agency grows. More accounts mean more follow-ups. More clients mean more reporting. More collectors mean more people updating information in different ways. Payment records become harder to reconcile, while important account details can end up buried in someone's notebook or chat history.
That does not mean every agency needs software from day one. But there are clear signs that manual tracking has stopped being practical. For Kenyan collection agencies, recognising these signs early can help reduce missed follow-ups, administrative work and poor visibility across portfolios.
How Manual Debt Tracking Works in Most Kenyan Agencies Today
A typical collection process may involve several tools at once. An Excel or Google Sheets file might contain debtor details, outstanding balances and follow-up dates. Collectors may use their phones for calls and WhatsApp or SMS for communication. Bank and mobile-money payments may then be checked and entered into spreadsheets manually.
For a small portfolio, this can work well. It requires little investment, and most teams already know how to use spreadsheets. The problem is that every additional account, collector and client portfolio creates more information to maintain. A spreadsheet does not know that two collectors have contacted the same debtor. A WhatsApp conversation does not automatically become part of the account history. A payment received today may not immediately update the outstanding balance across every record.
Eventually, the agency can spend more time maintaining its tracking process than using it to improve collections.
7 Warning Signs You've Outgrown Manual Tracking
There is no universal account number at which every agency needs software. The better question is whether the current process still gives your team enough control.
1. Your portfolio is growing faster than your team's capacity
If collectors spend a significant part of their day updating spreadsheets, checking payments and preparing reports, they have less time for actual collection work. A process that worked with a few hundred accounts can become difficult when the same team is handling thousands.
2. Follow-ups are being missed or duplicated
Collection work depends heavily on timing. A missed promise-to-pay date can affect recovery, while duplicated calls can frustrate debtors. If managers regularly ask, "Who last contacted this account?" or "Was this debtor supposed to be called today?", your tracking process may already be showing its limits.
3. Payment plans and promises to pay live in chats
A collector may agree with a debtor on a payment date or instalment plan. If that information remains in a WhatsApp conversation, notebook or personal spreadsheet, it becomes difficult for another team member to act on it. When a collector is absent or leaves, valuable account history can disappear with them.
4. Reconciling M-Pesa and bank payments takes hours
As payment volumes increase, teams may need to compare transactions with debtor records, identify the relevant account, update balances and investigate discrepancies. The issue is not simply recording that a payment arrived. The agency needs to know which account it belongs to, what remains outstanding and whether it matches the agreed payment plan.
5. Clients ask for reports you cannot produce quickly
Clients may want to know how much has been recovered, which accounts remain outstanding, how many promises to pay have been made and how individual portfolios are performing. If answering these questions requires several spreadsheets and hours of manual preparation, reporting becomes an operational burden.
6. You cannot clearly see recovery or collector performance
Managers need more than a list of outstanding accounts. They need to know which collectors are meeting targets, which portfolios are performing well, how much debt is ageing and how many promises to pay have been kept. When this information is spread across different files, getting a reliable picture takes time.
7. Staff turnover means account history gets lost
A collector may know why a debtor has not paid, what was discussed during the last call and when the next follow-up should happen. If those details are not recorded against the account, the next collector may have to start again. Over time, this creates inconsistent collection activity and unnecessary repeated calls.
The Hidden Cost of Staying Manual
Manual tracking is not free simply because the software licence costs nothing. The real cost can appear in staff time, delayed recoveries, reporting work and errors. For example, if four collectors each spend one hour a day maintaining spreadsheets, checking payments or preparing information that could be centralised, that represents around 80 working hours a month based on a 20-day working month.
There is also the cost of delayed action. A missed follow-up or incorrectly matched payment can affect more than administration; it can affect recovery itself. Data protection is another consideration. Kenyan collection agencies handle personal and financial information, so they need appropriate controls around how that information is stored and accessed.
A simple way to assess the cost is:
Cost of manual tracking = administrative hours × staff cost + estimated cost of missed or delayed recoveries
The goal is not to prove that software is always cheaper. It is to understand what the current process is actually costing the agency.
What Collection Software Actually Does — and Doesn't Do
Collection software does not replace collectors. People still need to make calls, negotiate payment arrangements, handle difficult conversations and decide what action an account needs next. The software provides structure around that work. A collection management system can centralise debtor and account information, organise follow-ups, record collection activity, track promises to pay and monitor payments. Managers can also gain a clearer view of portfolio and collector performance without asking every employee to prepare separate reports.
Instead of searching through several files to understand an account, a collector can work from one record containing its history, outstanding amount, previous activity and next action. The technology supports the collection process; it does not replace the judgement of the collector.
The Right Time to Switch: A Practical Decision Framework
Account volume
An agency managing a few hundred straightforward accounts may still find spreadsheets practical. An agency handling several thousand active accounts may have very different requirements. There is no fixed threshold. Portfolio complexity matters as much as account volume.
Team and portfolio size
Managing one portfolio with a small team is different from managing several client portfolios with multiple collectors. As more people access and update the same information, consistency and controlled access become increasingly important.
Operational pain
Use the seven warning signs as a simple test. If one or two happen occasionally, your current process may still be sufficient. If several happen regularly, it is worth evaluating collection software before the process becomes harder to fix.
Growth plans
Consider where the agency is going, not just where it is today. If you plan to take on larger portfolios, work with banks or other financial organisations, expand into additional counties or increase your collection team, implementing a structured system early can make that growth easier to manage. It is generally easier to organise a few hundred accounts than to untangle years of inconsistent records across thousands.
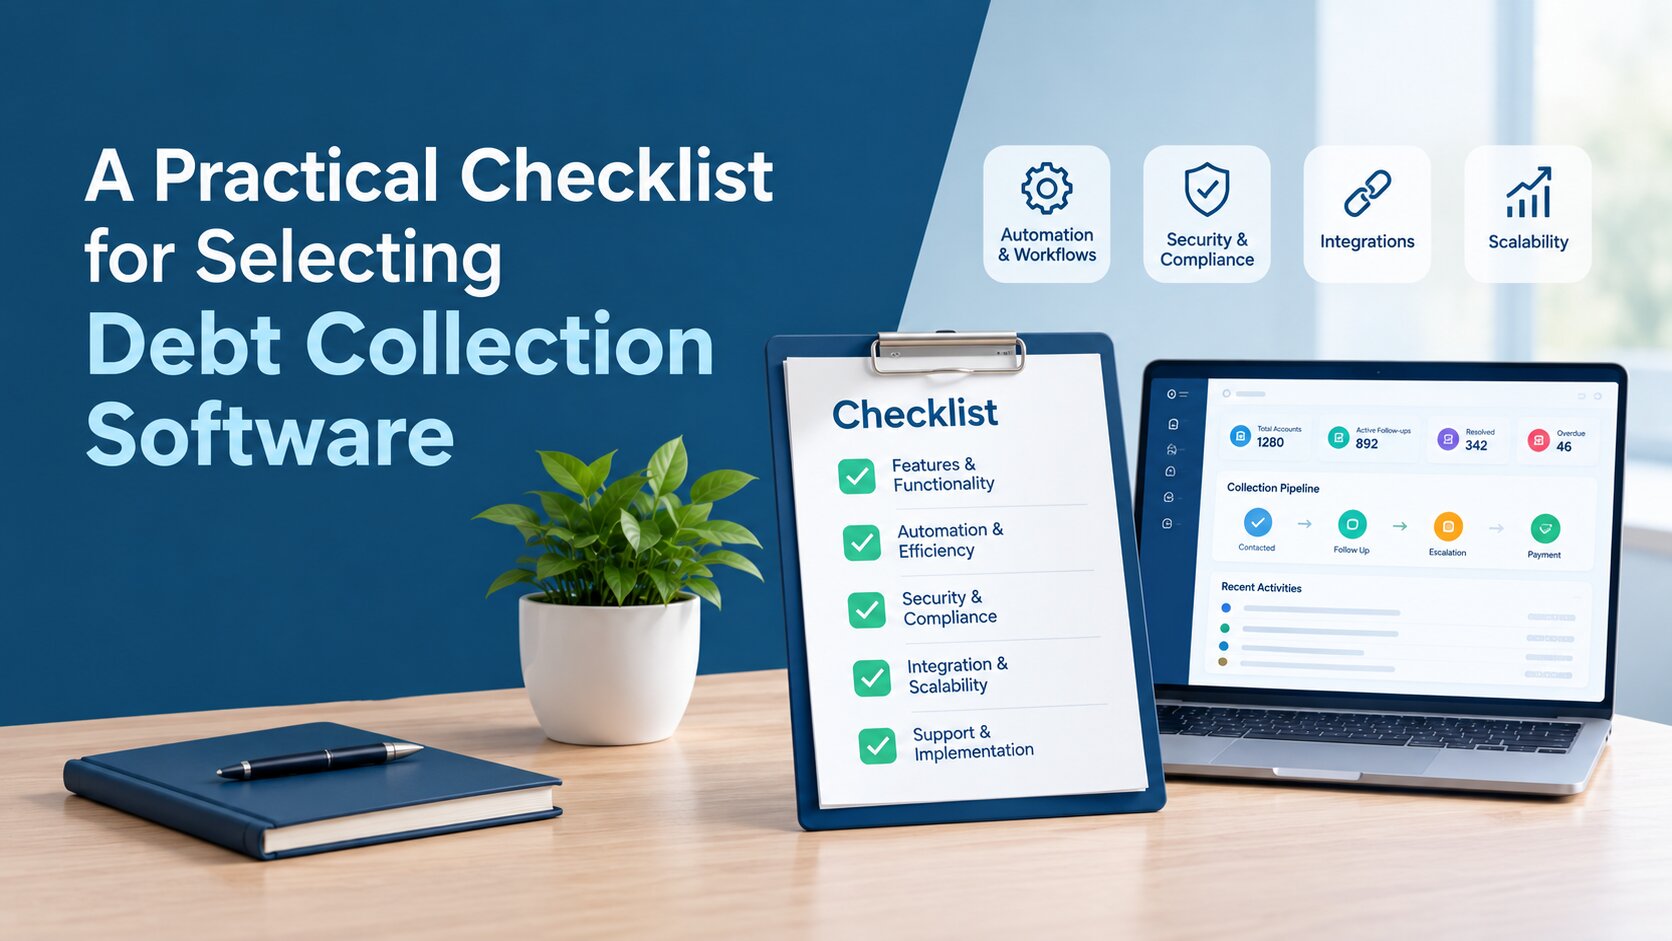
What to Look for in Collection Software: Buyer's Checklist
| What to look for | Why it matters |
|---|---|
| Easy-to-use interface | Collectors can adopt the system without extensive training. |
| Multi-client portfolios | Different client accounts can remain organised and separated. |
| Role-based access | Staff can access the information relevant to their roles. |
| Payment tracking | Bank and mobile-money payments can be connected to account records. |
| Follow-up management | Collectors can see upcoming actions and commitments. |
| Communication tools | Collection communication can stay connected to account activity. |
| Reporting and dashboards | Managers can monitor recoveries, ageing and portfolio performance. |
| Audit trail | Teams can see what happened on an account and when. |
| Data security | Debtor information needs appropriate protection and access controls. |
| Spreadsheet import | Existing account data can be migrated rather than re-entered manually. |
| Support and onboarding | Training and implementation support can improve adoption. |
| Transparent pricing | Agencies can understand the total cost before committing. |
Do not choose software based only on its feature list. Ask the provider to demonstrate your actual workflow: assigning an account, recording a call, creating a promise to pay, recording a payment, scheduling a follow-up and producing a client report.
That will tell you more than a long list of features.
How Smart Debt Collection by Beveron Technologies Supports Kenyan Collection Agencies
For a Kenyan collection agency, moving from spreadsheets to collection software is about more than storing debtor information in one place. The bigger need is to bring accounts, follow-ups, payment activity, collector performance and client reporting into a structured workflow. Smart Debt Collection by Beveron Technologies is designed for Kenyan collection agencies, financial institutions and lenders.
For a broader look at how debt collection software can support banks, MFIs and larger organisations, see Best Debt Collection Software in Kenya for Banks, MFIs & Enterprises.
The platform supports centralised debtor management, Excel and API-based data imports, customisable payment plans, automated recovery workflows, payment system integration and collection agent performance tracking. It also supports SMS, WhatsApp and calls for borrower communication, along with dashboards for collections, PTPs, agents, clients and recoveries. Teams can track payment histories, communication records, outstanding balances and recovery activity from a central system.
For agencies dealing with growing portfolios, these capabilities can reduce dependence on spreadsheets and disconnected communication channels while giving managers clearer visibility into account status and collector performance.
The right implementation will still depend on the agency's workflow, portfolio size and existing systems. Before choosing a solution, Kenyan agencies should confirm the payment integrations, data migration process, communication channels, security controls and integrations required for their specific operation.
How to Make the Switch Without Disrupting Collections
Moving from spreadsheets to collection software does not have to happen overnight.
Step 1: Audit your current process
Document how accounts are received, assigned, contacted, updated and reported. Identify where important debtor and payment information currently sits.
Step 2: Clean your data
Remove duplicates, correct incomplete information and standardise fields such as debtor names, account numbers, balances and contact details before importing the data.
Step 3: Start with one portfolio
A pilot lets the agency identify problems before moving every account. Choose a manageable portfolio and test the new process with a small team.
Step 4: Train collectors around real tasks
Show collectors how to find an account, record a call, update a promise to pay, record payment information and move an account to its next stage.
Step 5: Roll out and review
Once the team is comfortable, move the remaining portfolios across. Review recovery amounts, follow-up completion, promise-to-pay performance, ageing and collector productivity after 30, 60 and 90 days. The biggest mistake is treating implementation as simply installing software. The technology matters, but the process and adoption matter just as much.
FAQs
At what point should a collection agency invest in software?
There is no single account number. It is worth evaluating software when manual tracking regularly causes missed follow-ups, reporting delays, payment-reconciliation problems or excessive administrative work.
Is Excel enough for debt collection?
Excel can work well for small portfolios and simple processes. As accounts, collectors and client portfolios increase, however, it becomes harder to keep information consistent and maintain a clear view of collection activity.
How much does collection software cost?
Pricing varies by provider, users, account volume, features and implementation requirements. Agencies should compare the software cost with the staff time and operational costs of their current process.
How long does it take to switch from manual tracking?
The timeline depends on the amount and quality of existing data, the collection process and team size. Clean data and a phased rollout can make the transition easier.
Is debtor data safer in collection software than in spreadsheets?
It can be, provided the platform has appropriate security, access controls and data-handling practices. Software alone does not guarantee security, so agencies should assess how the provider stores and protects debtor information.
When Manual Tracking Stops Helping, It Is Time to Look at the Process
Manual tracking is not inherently wrong. For a small collection agency, spreadsheets and familiar communication tools can be a sensible starting point. The problem comes when the agency continues using the same process after its operations become more complex. Missed follow-ups, scattered account histories, lengthy payment reconciliation, slow reporting and limited visibility are all signs that the current process may be holding the team back. If several of these problems sound familiar, it may be time to evaluate dedicated collection software.
Explore Smart Debt Collection by Beveron Technologies and see whether a structured platform fits the way your Kenyan collection agency manages accounts, follow-ups, payments and reporting.
Best collection software for agencies in Kenya
Best debt collection management system for financial teams in Kenya
Best debt recovery software for corporate companies in Kenya
If you need a free demo of the best collection software for agencies in Kenya, please fill out the form.