How Can Saudi Collections Teams Manage Follow-Ups, Promises to Pay and Escalations?
A customer says payment will be made next week. Another asks for more time. A third has stopped responding altogether. For a collections team, these situations require different responses, yet they often end up in the same queue, competing for an agent’s attention. This is where overdue receivables become difficult to manage. The challenge is not simply contacting customers; it is knowing what happened during the last interaction, which commitment is due next and when an account needs a different approach.
For businesses in Saudi Arabia, a structured collections process can bring these decisions together. It connects three essential activities: planning follow-ups, monitoring promises to pay (PTPs) and escalating accounts when routine recovery efforts are no longer effective. The result is a more organised way to manage outstanding balances, make better use of agents’ time and give managers a clearer picture of collection progress.
Why Saudi Collections Teams Lose Track of Overdue Accounts
The biggest collection delays do not always come from customers refusing to pay. Sometimes, the team simply lacks a reliable way to move an account from one action to the next.
Consider a customer who agrees to settle an overdue invoice on a particular date. The agent records the conversation in a spreadsheet, but the reminder is saved in a personal calendar. When the payment date passes, the account remains untouched until someone reviews the file.
Multiply this situation across hundreds of accounts, and small administrative gaps become a serious operational problem.
Three issues commonly contribute to this situation.
Disconnected records. Customer details, payment history and conversation notes may be spread across spreadsheets, emails, messaging apps and accounting records. Agents spend time searching for information instead of deciding what to do next.
No clear next action. An account may have been contacted several times without a documented decision about the next follow-up. Agents may repeat the same request, while other accounts receive less attention than they need.
Inconsistent escalation decisions. One agent may refer a customer to a supervisor after a missed commitment, while another allows several additional extensions. Without agreed criteria, recovery decisions depend too heavily on individual judgement.
For Saudi businesses managing large receivables portfolios, these issues can become harder to control when teams work across branches, business units or Arabic- and English-speaking customer groups.
The solution begins with a simple principle: every overdue account should have a known status, a responsible owner and a defined next action.
1. Build a Follow-Up Strategy Around Account Priority
A useful follow-up process does not treat every overdue payment equally. It helps agents decide which accounts need immediate attention, which require a routine reminder and which need a more detailed review.
Prioritise accounts using three factors
Start by grouping overdue accounts according to:
- Age of the debt: A recently overdue invoice may need a reminder, while an older balance may require closer review.
- Value at risk: Larger outstanding balances may warrant additional management attention.
- Payment behaviour: A customer with a history of keeping commitments presents a different situation from one who repeatedly misses agreed dates.
Responsiveness and existing disputes can provide additional context. A customer who has raised a genuine invoice query may need the issue resolved before further collection activity can progress. These categories should guide prioritisation, not replace individual assessment. The purpose is to direct attention where it is most useful.
Establish a practical contact schedule
Once accounts are prioritised, define the expected action at each stage. The following is an illustrative framework that businesses can adapt to their contracts, customer relationships and applicable requirements.
| Account situation | Suggested action | Intended outcome |
|---|---|---|
| Payment has recently become overdue | Send a clear payment reminder | Resolve a simple oversight |
| First reminder receives no response | Make an appropriate follow-up attempt | Confirm the payment status |
| Customer requests additional time | Agree on a realistic next step and record it | Establish a commitment that can be monitored |
| Agreed payment date passes | Verify payment status and contact the customer | Understand the delay and decide what happens next |
| Repeated attempts do not resolve the account | Refer it for supervisory review | Determine whether a different recovery approach is needed |
The timing between these stages should reflect the business's policies and the circumstances of the account. A schedule should provide consistency without turning customer communication into a series of unnecessary reminders.
Make every interaction count
Before contacting a customer, the agent should be able to answer three questions:
- What is outstanding, and why is it overdue?
- What happened during the previous interaction?
- What specific outcome should this contact achieve?
The third question is particularly important. A call might be intended to confirm a payment date, clarify an invoice dispute or understand why a previous commitment was missed. Knowing the objective helps agents avoid repeating conversations that lead nowhere. After the interaction, record the outcome and the next action. This makes the account easier to manage if another agent takes over.
2. Turn Promises to Pay Into Trackable Commitments
A promise to pay provides a specific point around which the next collection action can be organised. However, the value of a PTP depends on how clearly it is recorded and whether the team follows through. Suppose a customer owes SAR 24,000 and agrees to pay SAR 8,000 by 15 October. The remaining balance will be discussed separately.
Recording only "customer promised payment" leaves important questions unanswered. How much is expected? When is it due? Does the commitment cover the entire balance? What should the agent do if the payment does not arrive? A useful PTP record should include the promised amount, due date, relevant payment details, the person making the commitment and the agent responsible for monitoring it.
Confirm what was agreed
Where appropriate, confirm the commitment in writing. The message should state the agreed amount and date clearly, along with any relevant payment instructions. This helps prevent misunderstandings and gives other team members a consistent reference if they need to review the account. It is also important to distinguish between a verbal commitment, an agreed payment arrangement and a payment that has actually been received. A commitment should not be treated as a completed collection.
Use PTP outcomes to determine the next action
Instead of treating all promises as successful or unsuccessful, classify them according to what happened.
| PTP outcome | What the team should do |
|---|---|
| Upcoming | Keep the due date visible and prepare any appropriate reminder |
| Fulfilled | Verify the payment and update the outstanding balance |
| Partially fulfilled | Reconcile the amount received and establish the next action for the remainder |
| Missed | Check whether payment is pending, contact the customer and review the reason for the delay |
| Rescheduled | Record the revised date and apply the relevant approval process |
This approach turns PTP tracking into a working part of collections rather than a record-keeping exercise.
What should happen after a missed promise?
The first step is to establish what happened. The payment may be delayed by an internal approval, a processing issue or a genuine change in the customer's circumstances. In other cases, repeated missed commitments may indicate that the current approach is not working. The agent should verify the payment status, document the explanation and determine whether a revised commitment is appropriate under company policy.
If the customer repeatedly misses agreed dates, the account may need a supervisor's review. Teams should establish clear rules for approving revised dates and handling repeated extensions instead of allowing each agent to make unrelated decisions. This creates a more consistent response while leaving room to consider the circumstances of individual customers.
3. Create Escalation Rules That Lead to Decisions
Escalation should not be viewed simply as the final step before legal action. It is a way to bring additional authority or expertise into an account when the current recovery approach is not producing a resolution. The most effective escalation process answers two questions: when should an account be reviewed, and who is responsible for deciding what happens next?
Define triggers before accounts become stuck
Businesses can establish review criteria based on:
- The number of days an account has remained overdue.
- The outstanding balance or financial exposure.
- Repeated missed promises to pay.
- A lack of response after appropriate contact attempts.
- An unresolved dispute or a failed payment arrangement.
- Circumstances that require approval beyond the agent's authority.
The thresholds should be documented and suitable for the organisation's portfolio. A high-value corporate receivable may require management review earlier than a small overdue invoice, depending on the business's risk policy.
Give each escalation level a clear responsibility
A simple escalation structure can help prevent accounts from being passed between employees without a decision.
- Collections agent: Handles routine contact, records responses and follows the agreed recovery process.
- Team leader: Reviews missed commitments, checks whether appropriate actions were taken and decides whether the current approach needs to change.
- Collections manager: Reviews higher-risk cases, significant outstanding balances and accounts requiring decisions outside the team's normal authority.
- Legal or senior management team: Assesses unresolved cases that may require formal recovery action, legal review or a wider commercial decision.
Not every account needs to pass through every level. The policy should explain when a case can move directly to a higher level and who can authorise that decision.
Separate internal escalation from legal recovery
For Saudi businesses, an internal decision to escalate an account is different from initiating formal legal recovery. Before pursuing legal action, the organisation should review the contract, supporting documents, payment history, any relevant dispute and the applicable procedure. The appropriate route depends on the circumstances of the claim and the requirements in force at the time.
Qualified Saudi legal counsel should confirm the appropriate process before action is taken. Collections software can help organise account records and document previous activity, but it does not determine whether a legal claim is valid or replace legal advice. A well-maintained record should make it possible to reconstruct the account's history, including contact attempts, agreed commitments, payments received, relevant approvals and the reasons for escalation. Access and retention should follow the organisation's policies and applicable requirements.
4. Connect the Process From Intake to Resolution
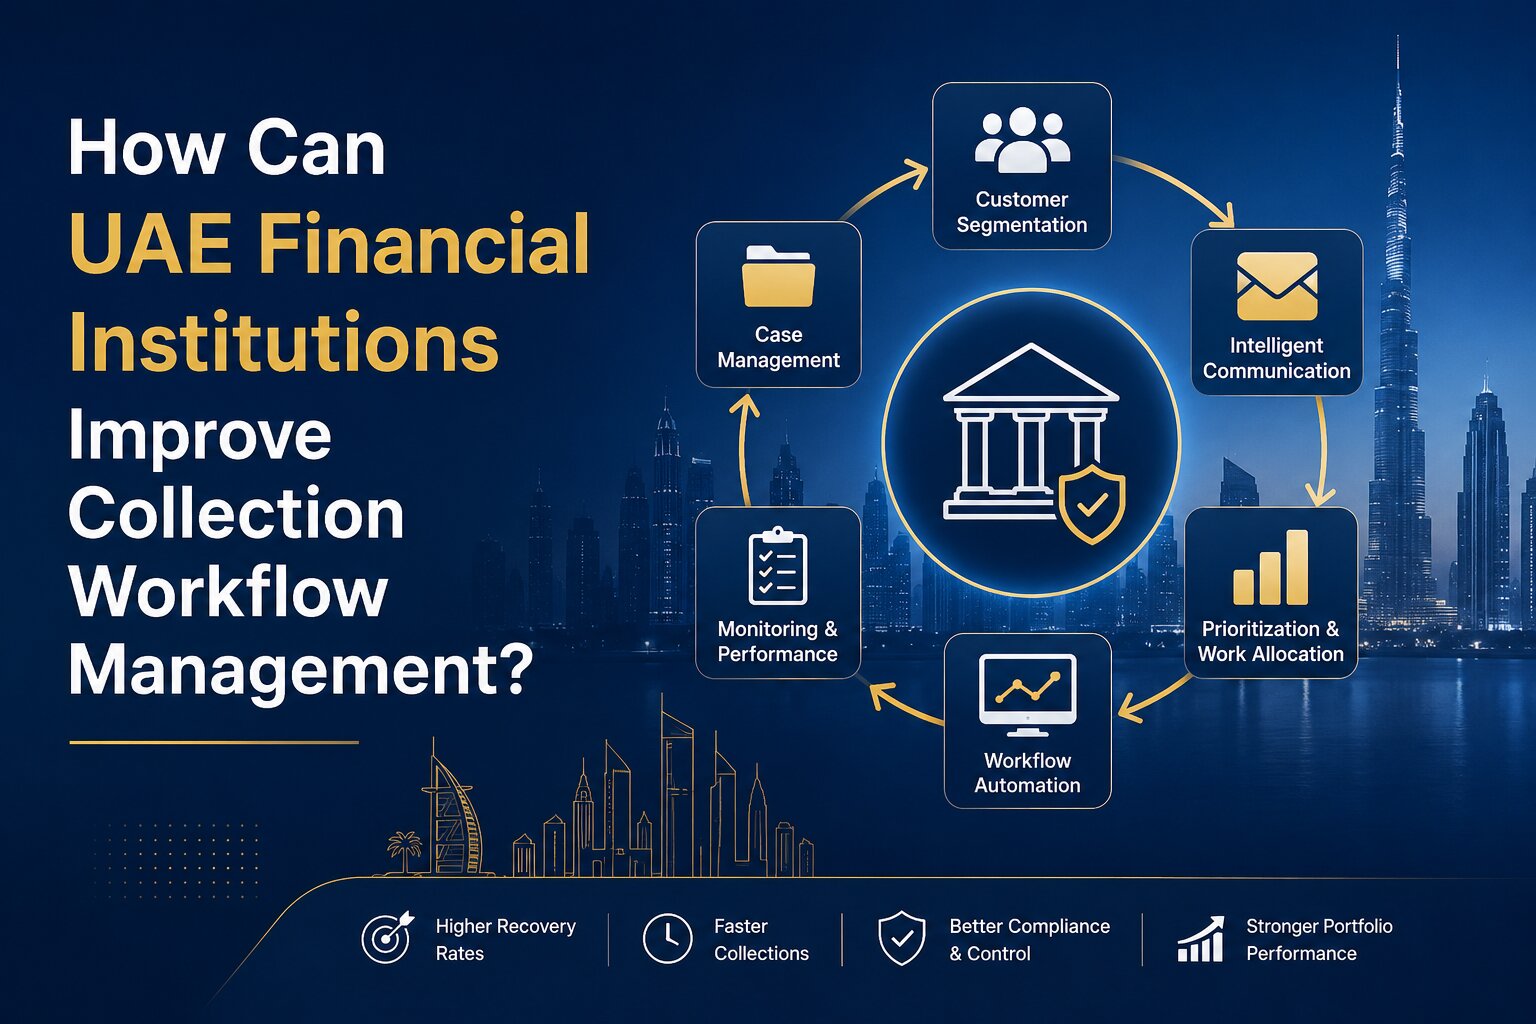
A clear collection workflow helps teams manage every overdue account without missing important steps. Start by recording the outstanding amount, payment due date, customer details and previous communication. Assign the account to a team member and set a date for the next follow-up. When the customer makes a payment promise, record the amount and expected date. If the payment is missed or the customer does not respond, move the account to the next stage for further action. Once the payment is received or the case is otherwise resolved, update the records. This connected process helps Saudi collections teams track progress, reduce missed follow-ups and understand which accounts need attention.
5. Use Collections Software to Reduce Manual Coordination
Once the workflow is defined, the next question is how to manage it consistently as the number of accounts increases. A small team may be able to coordinate a limited portfolio with spreadsheets and shared calendars. As the workload grows, however, manually maintaining every due date, commitment, contact record and escalation becomes increasingly difficult.
Beveron Smart Debt Collection is a debt recovery platform that businesses can evaluate when looking to organise collection activities within a structured system. The aim is to reduce the coordination work surrounding each account and help teams maintain a clearer view of outstanding actions. The following are key capabilities to assess when evaluating the platform. Exact feature availability and configuration should be confirmed with Beveron's product team.
Keep account information in one place
A centralised record can help agents review outstanding balances, previous interactions, payment commitments and current account status without searching through several files. This is especially useful when accounts move between agents or supervisors. The incoming owner can review the recorded history before deciding on the next action.
Schedule work instead of relying on memory
Collections software can help organise follow-up tasks and highlight accounts requiring attention. Depending on the system's configuration, reminders and task assignments can be linked to payment dates, account status or other defined conditions. Agents can then work from a prioritised list of actions rather than manually checking different spreadsheets and calendars.
Monitor commitments and flag exceptions
A structured system can make upcoming and overdue PTPs easier to identify. Once payments are reconciled against the account, the team can distinguish fulfilled commitments from partial payments and missed dates. This helps supervisors focus on exceptions instead of reviewing every account in the same level of detail.
Make recovery performance easier to review
Managers need to understand more than the total value of outstanding debt. They also need to see where the process is slowing down. Depending on the available reporting features, useful measures may include amounts recovered, overdue balances by age, PTP outcomes, outstanding tasks and accounts requiring escalation. These views can help identify whether delays are concentrated in a particular account category, stage of the process or team workload.
Assess language and local workflow requirements
For Saudi operations, businesses should assess whether a system supports their communication needs, internal approval process, access controls and reporting requirements. Arabic and English support, deployment arrangements and any required integrations should be verified directly with the provider. The best configuration is one that fits the organisation's actual recovery process while meeting its security, governance and operational requirements.
Manual tracking versus a structured collections system
| Area | Manual approach | Structured software approach |
|---|---|---|
| Account visibility | Information may be scattered across different records | Shared records provide a clearer account history |
| Work planning | Agents manage reminders and task lists individually | Tasks can be organised within the collection workflow |
| PTP management | Commitments require manual monitoring | Due dates and exceptions can be flagged for review |
| Escalation | Decisions may depend on individual habits | Defined criteria help standardise account reviews |
| Performance reporting | Data may need to be consolidated manually | Available dashboards can make trends easier to identify |
Software is not a substitute for sound collection policies or good judgement. Its value depends on how well the workflow is configured, how accurately staff record activity and how consistently managers act on the information available.
6. Measure Whether the Process Is Working
A collections process should be reviewed using a small set of meaningful measures. Tracking too many numbers without connecting them to decisions can create reporting work without improving recovery. The following five metrics provide a practical starting point.
| Metric | What it tells the team | How to use it |
|---|---|---|
| PTP kept rate | How often due commitments are fulfilled | Review whether agreed payment dates translate into actual payments |
| Contact rate | How effectively agents reach customers | Identify account groups or contact methods that may need attention |
| Recovery rate | How much of the relevant debt is recovered during a defined period | Assess collection outcomes against the chosen balance or target |
| Average days to collect | How long collection takes under the selected measurement method | Identify stages where accounts tend to remain unresolved |
| Escalation rate | How frequently accounts require a higher level of review | Investigate whether particular account types or process stages create recurring difficulties |
The definitions must remain consistent. For example, a PTP kept rate based on the number of commitments fulfilled differs from a rate based on the value collected against those commitments. Managers should also interpret the measures together. A high escalation rate might reflect weak follow-up, but it could also reflect a portfolio with unusually complex disputes. A low contact rate may point to outdated customer details, unsuitable contact timing or other barriers.
The useful question is not simply whether a metric has increased or decreased. It is what the result reveals about the recovery process and which action should follow.
7. Common Mistakes That Undermine Collection Efforts
Even a well-organised process can fail if agents and managers apply it inconsistently.
- Treating a promise as a payment. A customer agreeing to pay is not the same as the business receiving the funds. Keep commitments open for monitoring until you verify the payment status.
- Using the same approach for every account. The age and value of the debt, payment history and any unresolved dispute should inform the next step. Routine reminders are not always sufficient for complex or repeatedly delayed accounts.
- Allowing repeated extensions without review. Revised payment dates may be appropriate, but recurring missed commitments should trigger a review under the organisation's policy.
- Escalating without a clear reason. Supervisors need the account history, relevant evidence and a specific question or decision to address. Sending an account to another department without context creates more work rather than progress.
- Measuring activity instead of outcomes. The number of calls made can indicate workload, but it does not show whether the team is resolving accounts. Contact activity should be considered alongside actual payments, PTP outcomes and the time taken to resolve overdue balances.
A disciplined process gives agents room to handle individual circumstances while ensuring that decisions remain documented and consistent.
Frequently Asked Questions
What is a promise to pay in debt collection?
A promise to pay is a debtor's commitment to pay an agreed amount by a specified date. Collections teams should record the amount and due date, monitor the commitment and update the account when payment is verified.
How often should collections teams follow up on overdue accounts?
The frequency depends on the age and value of the debt, the customer's payment history, previous responses and applicable requirements. Businesses should define a suitable contact schedule and adjust it when the account's circumstances change.
When should an overdue account be escalated?
Escalation may be appropriate when an account exceeds a defined overdue threshold, repeatedly misses payment commitments, remains unresponsive or requires a decision beyond the agent's authority. The organisation should document its criteria and identify who is responsible for reviewing each case.
Can collections software automate follow-ups in Saudi Arabia?
Collections software can help schedule reminders, organise tasks, flag missed commitments and support structured escalation workflows, depending on its capabilities and configuration. Saudi businesses should verify language support, integrations, access controls and relevant compliance requirements before selecting a platform.
How do you track broken promises to pay?
Record each commitment with its amount and due date, then compare the expected payment against verified receipts. When a payment is missing or incomplete, document the outcome, investigate the reason and assign the next action according to the collection policy.
Conclusion: Make Every Collection Action Lead Somewhere
The difference between a reactive collections team and a well-organised one often comes down to what happens after each customer interaction. A follow-up should lead to a recorded outcome. A promise to pay should have a date and a monitoring process. An account that remains unresolved should reach the right person for review rather than stay in a routine queue indefinitely.
For Saudi businesses, connecting these activities creates a more reliable way to manage overdue receivables, understand recovery performance and make decisions based on the history of each account. Beveron Smart Debt Collection is worth evaluating if your team needs a more structured way to coordinate recovery activities and monitor outstanding actions.
Explore Beveron Smart Debt Collection to discuss how it could fit your collections workflow.
Best debt collection software for banks in Saudi Arabia
Best collections management software for collection teams in Saudi Arabia
Best accounts receivable software in Saudi Arabia
If you need a free demo of the best debt collection software for banks in Saudi Arabia, please fill out the form.